Showing posts with label Tom Powdrill. Show all posts

Sunday, December 08, 2024

"Private credit, public squalor"


Check out this Substack article in "The Social Factor" by Tom Powdrill regarding the attempt by the owners of a food manufacturing company in Wrexham, North Wales to cut the terms and conditions of its workers by "fire and rehire". 

I have contacted Newham Council Pension Officers and the London Collective Investment Vehicle (LCIV} about this. By coincidence I was brought up near Wrexham and have some experience of the impact of "fire and rehire". Thankfully the new Government is consulting on how to effectively "ban" such dismissals in the future. Hat tip picture to Herald, Wales

Private credit's link to fire and rehire in Wrexham may open up more questions

Ryan Reynolds has made Wrexham AFC internationally famous. His co-ownership of the club, and the Welcome To Wrexham TV series, have made the club visible to millions of people. But there’s another increasingly high-profile drama, involving a change in ownership, playing out in Wrexham - the takeover of food producer Oscar Mayer by private credit manager Pemberton Asset Management.

Oscar Mayer operates several sites including one in Wrexham. Pemberton became an 85% owner of the business in 2023, having previously been a lender. In 2024 Oscar Mayer has proposed reduced terms and conditions in new contracts under threat of dismissal, known as ‘fire and rehire’.

The workforce is fighting the changes and 550 workers have been on strike. They recently voted 97% in favour of continuing strike action. These are not well-paid workers, so the proposed cuts are going to hurt. Not surprisingly, the dispute is a big deal in Wrexham.

Wrexham is linked to the dispute in another way. Clwyd Pension Fund, which includes Wrexham council workers, invests in a private credit fund via the Wales Pensions Partnership (WPP), the local LGPS pool. That fund, run by Russell Investments, in turn allocates money to underlying managers including Pemberton.

Understandably, there is a reluctance on the part of councillors representing wards in Wrexham to award money to an asset manager that owns a company that is cutting the pay of workers in Wrexham under threat of getting the sack. Private credit is a popular asset class and there are plenty of other managers available. Clwyd has confirmed it won’t be giving Pemberton any more money and will engage with WPP over the issue.

Oscar Mayer may be an indicator of future flashpoints. As noted, private credit is a hot asset class. Every asset manager now seems to want a piece of the pie and in turn lots of pension funds have made allocations to Pemberton and other managers. Because of the type of companies they lend to, it shouldn’t be surprising that some struggle financially. Nor should it be a surprise that the floating rate nature of the loans that are prevalent in private credit can push up borrowing costs quickly.

The IMF’s Global Financial Stability Report notes “The transmission of higher rates into firms’ cost of debt has been more swift for firms with variable rate debt” and “Private credit borrowers almost exclusively use floating rate loans. By contrast, only about 29 percent of high-yield corporate bond issuers’ total debt is variable rate.”

It’s possible that we’ll see more cases like Oscar Mayer where the lender ends up becoming an owner. Some managers combine both PE and private credit under one roof but others like Pemberton focus on lending. Without a PE background such managers probably have don’t have expertise in owning/running an investee business and so in a crunch may reach for How To Cut Costs For Dummies without thinking through the reaction from the workforce.

Simply repeating “this business is in difficulty, these changes are unpleasant but necessary” and not budging is recipe for a prolonged dispute. Anyone with a basic understanding of industrial relations - which some private credit managers may simply not have - knows this is where you start from, not end. Other private credit managers might think of Oscar Mayer as an example of how not to do it.

In turn, pension funds and other asset owners may find themselves caught up in similar disputes, since the circumstances that result in a lender becoming an owner are unlikely to be brilliant. And as the Clwyd example shows, there is a risk of a problem showing up on the fund’s doorstep.

For asset managers and asset owners I can see this asset class has the potential to chew up carefully curated ESG / Responsible Investment credentials without a much clearer sense of how they will handle workforce issues when, inevitably, a portfolio company ends up in trouble".


Saturday, October 08, 2022

Labour standards in the rubber glove industry

Last week I chaired a virtual webinar organised by PIRC and UNISON on Labour standards in the rubber glove manufacturing industry. There were 6 panel members located in Europe and Asia and an invited audience of  some 50 industry representatives, investors, trade unionists and NGOs. 

There was some dreadful horror stories of human rights abuses in many factories that produce gloves for the NHS (and which Local Government Pension Funds may also have investments in).  Hopefully there will be a follow on event soon. 

This was my introductory blurb. "Hello everyone and welcome to today’s webinar on labour standards in the rubber gloves industry co-organised by PIRC and UNISON.

Since the start of the Covid-19 pandemic, and the greatly increased demand for personal protective equipment, there has been an increasing focus on the medical rubber glove supply chain. Forced labour, poor conditions and other labour rights concerns have received considerable media exposure.

For investors there has been a bit of a rollercoaster ride. The share prices of manufacturers initially surged on increased demand, but public policy responses brought valuations back to earth. In particular the use of Withholding Release Orders by US Customs and Border Protection to address the use of forced labour had a major impact. In the future public procurement decisions by national and regional public sector buyers may become increasingly important. While the S in ESG is often the poor relation, and is given less scrutiny by many investors, in this case risks relating to poor labour practices has become financially material.

It’s also difficult terrain for investors to navigate, due to differing accounts of the situation on the ground. Companies have tried to improve. On some key issues – such as the use of recruitment fees – a substantial amount of money has been spent seeking to provide redress. Yet workers, activists and unions continue to raise significant concerns.   

In this webinar we will hear from a range of experts and organisations involved in improving standards in the rubber glove industry. In the first half we’ll be hearing about ongoing concerns relating to labour practices in the sector.


Anton Marcus –Trade Zones & General Services Employees Union

Andy Hall – migrant workers' rights advocate

Tom Grinter – IndustriALL

Then we’ll take some questions. You can put these either in the chat or use the Q&A function.

In the second half of the webinar we’ll focus on some of the policy responses, including public procurement, and the business-led initiative the Responsible Glove Alliance.

Pauline Gothberg, Swedish County Councils and Regions

Nusrat Uddin, Wilson's solicitors

Anna Pienaar, Executive Director, Responsible Labor Initiative & Responsible Glove Alliance

Then we will have the opportunity for further questions.

To start us off, Tom Powdrill from PIRC is going to give a very brief introduction to its work on this topic...

(I am moderating another Labour Standards investor event on 18 October "LAPFF & IndustriALL Webinar: Employment injury insurance for garment workers in Bangladesh. Registration here)

Tuesday, February 01, 2022

1st anniversary of the coup in Myanmar - TUC Statement


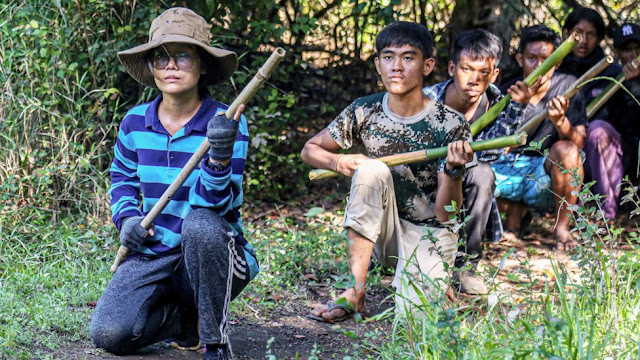
Picture from this BBC report on young people training to fight the vile military dictatorship in Myanmar. Below is TUC statement. It is good to see that Total are withdrawing their operations in Myanmar. Not so 14 years ago. I must find out which garment companies are still investing there. @TomPowdrill - any thoughts?

"1 February 2022 marks the one-year anniversary of the seizure of power of a military junta in Myanmar, deposing the legitimate government in a coup d’etat. The TUC expresses our admiration for all the democratic forces, including the trade union movement, which have bravely resisted the military at great cost to themselves. 

We warn against any normalisation of the illegitimate junta and reiterate our call for diplomatic recognition of the National Unity Government in its place. We also echo the calls of the international trade union movement to target the military government economically. In particular, by placing embargos on the sales of arms and aviation fuel to the Burmese military and cutting off its revenues by refusing to purchase Burmese oil and gas.  

We welcome the decision by Total and Chevon to withdraw from their operations in Myanmar - and urge all other oil and gas stakeholders to do so too.  

To private sector enterprises in the garment trade, including several British brands, who purchase stock from Burmese textile factories, we raise the issue of the human rights abuses, political violence, and union busting taking place in these factories, communicated to us by our Burmese sister centre, the CTUM.  

We believe, based on the information provided to us by the CTUM, that any realistic assessment of whether companies can actually exercise human rights due diligence in their supply chains, including by protecting the trade union organisations in the factories, will show that it is currently impossible to meet the obligations of the UN Guiding Principles on Business and Human Rights. That being the case, companies should cease all new orders and make arrangements to withdraw their business in a responsible manner". 

Tuesday, November 12, 2019

Labour and Capital - A Left Platform

Hat tip post Tom P (I picked image : Capital and labour, by Henry Stacy Marks)

"It's election time. I'll have a look through party manifestos when they're out to pull together policy commitments that are relevant to this blog. In the meantime, here are a few rehashed thoughts about what I'd like to see as a Left platform.

1. Employee representation at board level.

The Conservatives' botched reform in this area has left the door open to further reform. As the failure of most companies to appoint employee directors shows, this is not going to be achieved through 'comply or explain', especially when some asset managers will likely lobby against. So legislate for it. Minimum of two on each board.

2. Redefine directors' duties.

This is straightforward, but important. As I saw someone comment recently, Section 172 as it stands actually made shareholder primacy explicit, even as it was pitched as 'enlightened shareholder value'. Check out the previous version (which put employees on a par with shareholders) to see how it changed. I am comfortable with the idea that the duty it simply to promote the success of the company, taking account of all stakeholder interests. If you don't think the current version is a problem, have a read of some justifications for exec pay and tax avoidance that prey Section 172 in aid.

3. Pre-distribution.

Pretty obvious that the big battle over the future of the firm is about different claims on resources. Pre-distribution got a bad press when Ed Miliband floated the term back in 2010-2015 parliament, but the idea is a sound one. Ensuring that labour gets a fairer share up front, rather than relying heavily on transfers, is likely to be much more politically durable. This suggests enhanced bargaining power (so let's make it easier for workers to form unions, and easier for unions to gain recognition and bargain).

But we also need to look at other mechanisms for ensuring a greater share of wealth goes to working people at the point it is created. Labour's Inclusive Ownership Funds provide one interesting model, and would create a who new class of investors which could have some interesting corpgov outcomes (for example in takeover situations). I see a lot of people speak positively about greater employee ownership in theory, so this idea ought to be popular. Those who criticise it should come up with alternatives. And if an IOF style scheme isn't applicable there should be mandatory profit-sharing.

4. Radical executive pay simplification.

Everyone in corpgov these days says they support pay simplification, but in practice most companies still have several incentive schemes. Nor am I convinced that deferred share awards get us anywhere because I don't think they will have much of a motivational effect (and I'm impressed by Sandy Pepper's work in this area). I'd scrap as much variable pay as possible. If we can't get rid of it all restrict the variable bit to small short-term cash bonuses with clawback and malus provisions. Much easier for all to understand, and hopefully easier to reclaim if something goes wrong.

5. Rebuild democratic control of capital.

Several trends in UK pension provision have served to less or remove democratic control of pension assets. The 'professionalisation' of governance is a good thing in general, but if it serves to cause the link with beneficiary interests to be broken we have a problem. In the ESG world I worry that this has led to priorities being adopted that are more aligned with the interests of those running money than those of whose money it is. So I would like to see reinvigorated member/beneficiary involvement in all types of pension provision.

6. Democratise shareholder voting

I can't see any good reason why asset managers can't find a fintech solution that allows asset owners, or retail investors, to vote in pooled funds. The current situation is ridiculous, especially in a world where more and more money is managed passively. If I'm only employing you to hold the index, not pick stocks, why should I be forced to adopt your views views on corporate governance? It makes no sense.

7. Radical disintermediation.

One for a decade ahead. Will we actually need asset managers in the future as they exist in their current form? Could passive management be a utility? Could we do it ourselves?

Posted by Tom Powdrill at 21:50

Friday, May 12, 2017

National Express - 6 kids die but CEO still gets 7 figure bonus. Wtf?

A sensitive and thoughtful commentary below by Tom Powdrill on his blog "Labour & Capital" about the many governance dangers of paying huge "performance related" bonuses to Chief Executives. 

National Express of course has been warned on numerous occasions on this blog and others about the dire health & culture in its USA school bus arm. 

Did the CEO of National Express actually do anything about this? 

No wonder so many people in the UK and the USA hate the "establishment" and vote for extremist politics. 

Internal logic versus external stupidity

"I've blogged about National Express a few times over the years, mainly in relation to its anti-union activity. But today a story in the FT about its executive pay arrangements caught my eye. I think it's a great example of why performance-related pay is a colossal waste of time, including trying to tie pay to ESG targets.

As many people may know, there was a tragic accident in the company's US school bus business last year in which six young children died. This is clearly pretty much the worst safety outcome a company that transports children can have.

Understandably, therefore, the company has reduced to zero the amount of the chief executive's bonus that is tied to safety. But, he's still going to get the rest of the bonus, which equates to over 150% of salary. Some shareholders are ticked off, and think that the company should not have paid any bonus at all, sensing that a chief executive getting a seven figure bonus in the year when the company suffered multiple child fatalities is not a good look.

To me, this sort of outcome is the inevitable outcome of the performance-related pay delusion. If you set multiple targets for variable pay you are always going to get these kinds of perverse outcomes. If you've hit your financial targets but there have been fatalities then simply not awarding the bits of pay tied to ESG criteria is logically what you should do. But it looks appalling. Applying some common sense has its own problems - for people within business/finance at least. If you scrap the bonus entirely (which is what I think they should have done) then it makes plain what a joke the system is - it is incapable of delivering sensible outcomes.

This isn't the first time this has happened in relation to fatalities involving a PLC. The CEO of Thomas Cook got in a similar mess by giving up some, but not all of her share award. To try and stick to a logical/statistical approach merely invites the question "so how many people would have to die before you didn't take any bonus/share award?". Companies - or investors - that simply hide behind the incentive design look inhumane.

There was a similar example with News Corp when the hacking scandal blew up - with James and (I think) Rupert Murdoch agreeing to give up some, but not all, of their bonuses. And, more generally, when there is a lag between performance and reward (because shareholders have asked that reward be tied to slightly more long-term performance) you get examples when exec awards vest despite performance having subsequently turned bad again.

I know I am well out of step with many ESG people here, but to me the fundamental problem is the insistence on performance-related pay. Quite aside from motivational issues, perverse incentives and the whole question of why the most highly paid need or deserve further incentives to get them to do their job, performance pay generates these ridiculous outcomes. They make sense according to the text book internal logic of incentive schemes but they look terrible to any half conscious actual human being. Instead of wasting even more time trying to tie ESG criteria to pay we should be scaling back variable reward if not scrapping it altogether.

Tuesday, October 06, 2015

Fidelity pays £50,000 to help Tories cut tax credits for children & increase tax breaks for millionaires

Check this post by financial blogger Tom Powdrill and look for "Fidelity"in my blog archive. See what is being done with profits from managing our money. If your pension scheme has any links with Fidelity ask them to think again.

"Another Fidelity - Conservative Party link

I've blogged a lot previously about the many links that exist between the asset manager Fidelity and the Conservative Party. I've just discovered a new one that provides a bit more insight into how significant the relationship is.

The Leader's Group is one of the Tories' donor clubs. In fact, according to their own blurb, this is the "premier" supporters group:

Annual membership: £50,000 Chairman: Howard Leigh

The Leader’s Group is the premier supporter Group of the Conservative Party. Members are invited to join David Cameron and other senior figures from the Conservative Party at dinners, post-PMQ lunches, drinks receptions, election result events and important campaign launches.

It's not cheap either, at £50,000 for an annual membership. Helpfully the Tories provide some data on who meets who in this club, and look who turns up in their disclosure for Q4 2013:

FIL Holdings (UK) Ltd (represented by Barry Bateman, Director )

I had vaguely heard of Barry Batemen so I had a google around, and it turns out he's the vice-chairman of the UK business. This is a very senior position in the firm.

So in addition to funding the Conservative Party, employing a Conservative MP, sponsoring meetings of the Conservative Party's business liaison organisation and voting in favour of PLCs making political donations to the Conservative Party, Fidelity had one of its most senior UK people at an event organised by the Conservative Party's "premier supporter group".

Saturday, August 09, 2014

The Best of Old Labour Should Now Be New Labour

Please read this excellent post by Tom Powdrill at Capital & Labour on his holiday review and modern day comments of the book "Economic Priorities for a Labour Government" by Roy Hattersley, which was published in 1987.

Compare our present economic model to what Roy was recommending.

No wonder countries which have greater equality and industrial democracy such as Germany, Norway, Finland and Sweden have more successful economies than us.

It appears to me at least that the Labour Party under Ed Miliband must continue its journey to re-balance British politics and economics away from the view that unfettered neo-liberalism is best.

Those of  us who genuinely believe in a mixed economy ought to shouting out loud that "the emperor has no clothes".

Tuesday, September 24, 2013

#Lab13 - Responsible Capitalism and Workplace democracy. Giving workers a real voice

This interesting lunctime fringe had been sponsored by the Fabians, TUC and PIRC. Chaired by Seema Malhotra MP.

TUC General Secretary Frances O'Grady started off by saying some of her members think that "responsible capitalism" is an Oxymoron! But her main point was why is corporate governance in the UK so peculiar and out of step with the rest of Europe?  Where employee representation on company boards is common place.

We need to rebalance Labour and Capital. Frances quoted a terribly condescending and even insulting comment (which she described as "patronising twaddle") from the CBI about why in the UK British employees aren't good enough to being represented on boards.  Workers keep being told that they are the organisations "greatest assets". Yet the arguments being made against employee representation remind her of those made in 19th century against getting rid of the property qualification in order to vote.

Chuka Umunna MP believes that it is all about balance. Do we want a mixed or a laissez faire economy? Leading businesses started talking about this debate before we did in Parliament. Things have got to change. Need to promote the long term. Value investment in people and skill up. Look at the damage done to BP reputation and profitability after the oil disaster. It is in companies self interest to have good governance models. 

Tom Powdrill from PIRC thought that the governance mascot was Lord Myners. Why did shareholders not stop the banks from destroying themselves? Excessive executive pay levels are being driven to the levels found in financial markets. Since oversight is not by shareholders but by fund managers and hedge funds who naturally will think such levels are appropriate. Need a dose of reality. Tackle the problem up stream before a decision is made.  UK Companies already invest in Europe where employee representatives are widely accepted -so why don't they support similar models over here?

Nita Clare from the IPA (see previous post here) was Tony Blair's advisor on trade unions and before that a national officer for unison for 17 years. Good businesses know the value of stakeholders. The CBI quote is now quite old fashioned.  She stressed the importance of the supply chain to business. If there is a fire in a Bangladeshi factory it is no use saying "nothing to do with us".

There has been a death of deference and trust at work. 60% of employees surveyed said they don't trust managers. Management style is critical. If you have a culture of fear in any organisation, private or public, then it will fail. The Social partnership approach in Germany will be difficult to adopt in UK

My question to the panel was similar to the one I made before was how is it that I am an employee representation on a £900 million pension scheme and I sit on a joint committee on health and safety that looks after the safety of thousands of workers but I cannot sit on the management board or remuneration committee of my organisation?

Wednesday, August 15, 2012

"Barclay pay AGM vote round-up"

Hat -tip Tom at "Labour & Capital"

"Being the sad man that I am, I've been collecting asset manager voting decisions on Barclays' remuneration report at this year's AGM.

Here are the scores on the doors so far -

FOR - Goldman Sachs, Standard Life
ABSTAIN -
OPPOSE - Aberdeen, AXA, F&C, Investec, JP Morgan, Jupiter, Kames, Legal & General, M&G, Royal London, Scottish Widows

Will update when I get more data. Interesting thing to note is that some hefty UK institutions voted against. So where did all those votes in favour come from?"

(grayee comment: Goldman Sachs Yeah but Wtf is Standard Life doing voting to reward shareholders being ripped off?

Friday, December 02, 2011

LAPFF Conference 2011: The Continuing Crisis

Another early start on Thursday to get to the Local Authority Pension Fund Forum (LAPFF) 16th annual conference in Bournemouth from East London for 9am. LAPFF “exists to promote the investment interests of local authority pension funds, and to maximise their influence as shareholders whilst promoting social responsibility and corporate governance at the companies in which they invest....Formed in 1990....combined assets of over £100 billion”.

It is of course quite ironic that this conference took place less than 24 hours after I had been on a (number of) picket lines in the biggest industrial dispute since 1926 over pensions.

Both of the local government pensions schemes I have an “interest” in are members of LAPFF. This year for the first time I was at the conference as a Councillor rather than as a Staff side representative. Which caused some confusion. I’ll try and post on as many of the excellent presentations and debates as possible. If you are a member of a local authority pension committee or panel in any capacity (and any Party or Union) then this is the conference to come to. It is politically non-partisan which in this context I think is very much a good thing.

Tom Watson MP was to be the opening speaker but his mum has fallen ill so he has had to send his apologies. The Chair of LAPFF Cllr Ian Greenwood and PIRC Tom Powdrill instead did a presentation on “The Hacking Scandal: Lessons for Investors”.  

LAPFF have been trying to remove James Murdock (son of Rupert) as Chair of BSkyB not so much with regard to the appalling behaviour of News of the World reporters etc but concern about his independence and the reputational risk to our investments and what this is doing to shareholder value. For example will OFCOM still consider NewsCorp to be a fit and proper shareholder of BSkyB? If they don’t - what impact will this have to Pension fund investments in BSkyB?

Wednesday, November 09, 2011

Sticking two fingers up over executive pay

Tom (as usual) making some good points about controlling Executive pay.  Picture of a City Banker taunting NHS doctors and nurses with a £10 note as they passed Deutsche Bank
while on a demonstration earlier this year.

"...One of the great achievements on the New Right was atomisation, so people at work think more in individual terms, and less in a collective sense. I don't mean this in any kind of conspiratorial sense - people on the Right believe this is how people should think - but it's an achievement they don't want to lose.....

There is some ground opening up here for Labour as many in the party would be actively enthusiastic about employee involvement in (remuneration committees), so this could become a bit of a wedge issue, at least in my little corner of the world. Although asset managers and the investor representative bodies won't like it, there is definite interest in the idea that is starting to bubble up.

More generally there is also a sense that patience is running out. There are only so many times you can call on the executive class to exercise restraint and they stick two fingers up. There are only so many times you can urge asset managers to take a tougher line and they shrug their shoulder and say there's nothing much they can do about it. Of course we've been through all this before, and nothing has changed, so therefore shouldn't we just expect it to carry on? Well, maybe, but it was a former FTSE chief exec who said in a conversation recently that the position of executives taking ever more out of companies as their reward was analogous to the position of the unions in the 70s. People moaned for a long time about TU power before anything happened, but when change came it was very significant.

I now think that we could see some fairly radical reform in respect of executive pay, whether it happens under the Coalition or the next Labour govt in 2015 ;-) I suspect it will go significantly further than the policy positions adopted by most of the 'professional' governance bodies because most of them are still stuck parroting the disclosure+shareholder empowerment model (which hasn't worked very well). There has been an opportunity since the crisis to think very differently, our sector hasn't really done that. Don't be surprised if what we thought were the ground rules of the exec pay debate get overtaken by events".   

Check out full post here on Labour and Capital here

Wednesday, January 19, 2011

TUC Trustee Pensions Conference 2010: “Shareholder Resolutions”

This post is yet another very late "catch-up".  The  annual TUC Pension Conference is the "Trustee" event of the year.  It was held at Congress House in London on 22 November 2010 and was packed out.

I missed most of the morning due to a regional committee meeting and came in during the end of the Stewardship Panel Q&A. 
I then went to a workshop on “Shareholder Resolutions” led by Tom Powdrill from PIRC, the notoriously shy and retiring UNISON National Capital Stewardship officer, Colin Meech and Unite National officer, Jack Clarke (see above left to right).

Tom explained that in December 2010 fund managers must explain why not or publish their voting record at the AGM’s of the companies whose shares they “hold” on behalf of investors.

To be able to table a motion at a British AGM you need 5% of total voters or 100 x £100 nominal value (Nominal £10k). You must table this motion within strict time limits to prevent the company charging you the full costs of circulating details of your motion.

There have been 8 Environmental Social and Governance (ESG) motions in the last 5 years. Mostly led by trade unions. Warning that many companies see such motions as a confrontational tactic. So you should try and make it appear constructive? Not "anti-company". Instead of appearing to give instructions make suggestions. However, direct motions may well be the only realistic option if companies are being unreasonable. To get the vote out you must contact all major shareholders, investor representative bodies and meet them - preferably face to face.

But you must demonstrate you have tried to engage with the company first. Note fund managers generally vote against ESG motions. Even those who claim to be supportive of ESG principles.

The LAPFF "Marks and Spencer" motion against a combined company chief executive also being the company chair was a landmark occurrence. There had been significant engagement beforehand about best practice. Stuart Rose now says that it was his worse mistake (not to separate the roles of Chair and CEO). Marks and Spencer have now a separate Chair and CEO and comply with best practice. The panel were "disappointed" that L&G tracker fund managers voted against this (why on earth did L&G do this?) and that they had 4.5% share of the company. Remember that there is only usually 50% turnout of shareowners at AGM's.  So you can have a greater affect even if you only have control of a smaller number of shares.  The ESG motion on anti-trade union activities of First Group in the USA did result in significant change in company behaviour.
Colin talked about the Fair Pensions BP/Shell Tar Sands motions and the UNISON staff pension fund which helped bring it about. UNISON staff pension scheme has a broad screening programme such as not to invest PFI contractors.They cleared the proposed motion with the Canadian PSI trade unions beforehand. The motion fitted UNISON policy on climate change. It was crucial to get the support of the large American public sector funds. 45% global pension funds are in the USA. He reminded us all of the Freshfields legal opinion's that such “responsible” investment is a fiduary duty of Trustees. Colin recommended the book Hawley and Williams “The Rise of Fiduciary Capitalism”.

Jack Clarke pointed out that Unite spend 10% of their budget on organising. He talked about the Meat workers campaign. They gained 10,000 new members and 250 new stewards. A key issue was agency working. Agencies undercut permanent workers and exploited staff. The Union wanted equal treatment. They worked on a supply chain strategy. 85% of the meat market goes to retail shops. They pushed Tesco and other large UK retailers in a pincer movement, above (by share motions) and below (from workers). Tesco is a key market driver. They tabled a solution at the AGM with West Yorkshire Pension Fund on this issue. 11% shareholders voted in favour and 7% abstained. There was widespread press coverage. ASDA signed a deal with Unite for equal treatment in the UK and Ireland. 50,000 workers affected in the UK and gained parity of pay and were now usually made permanent after 13 weeks agency work. Lessons: Resource intensive; you need to have economic as well as morale case. Needs to be more active engagement with trade union trustees. It is vital to deliver bottom up pressure on fund managers.

Saturday, December 04, 2010

LAPFF Conference 2010: Stewardship Code: Putting it into practice

Tom Powdrill (PIRC) led a panel discussion about putting the Code into practice. David Murphy (NILGOSC), Tony Little (Gartmore) and Iain Richards (AVIVA). The Code came out of the Walker Report and is a response to the financial crisis. Not a fluffy “feel good” report but an attempt to try and prevent a future financial crisis. Can shareholders control companies? If shareholders cannot then look at Ireland were due to voluntary failure there is now a regulatory approach to governance.

David spoke first about his scheme. There are 204 employers, over 80,000 members and £3.6 billion assets. They support the idea that they are asset owners; they are the ultimate owners and should take responsibility for what has gone on in the past. They believe in co-operation and the importance of disclosure. They vote in all markets and report back on investment policy. Be open and transparent.

Tony explained that Gartmore are mainstream investors in 2,500 equities around the world. He was struck by the difference between this report and the UK governance report Cadbury which said this is what good practice looks like and others should aspire to it. The Stewardship Code “horse trades”. This is what you should be doing. Will see what good practice eventually looks like. The EU intervention has been negative rather than positive. They have forced the pace. They want to regulate. His role often is to be candid friend.

Ian said there may be over blown expectations of the Code. It was to resolve the “absentee landlord” problem in the run up to crisis. But there is an issue of resources. They have 7 in his team but this is still limited. Conflicts still exist; there are still misaligned incentives, short term structural problems. There are differences of objectives in engagement. In the UK 13% of shares are owned by pension funds and 13% by insurance funds. But it is only 26% of market. 40% of UK now owned by overseas investors. Concern around the role of the ISS.  An unaccountable organisation who admits looking after its primary audience - US investors. An awkward question is what do fund managers do? They have already signed up to the Stewardship principles. Is it transparent to have such long policy statements? Principle 7 (reporting on what they do) is the most important. There is a poisonous view that all you have to do is delegate everything to fund managers – and job done. This leads to apathy.

Next Q&A. I asked a question about how the new Code will not last be last word on governance and will evolve and change. Panel members have hinted at things that could be done better. What one significant improvement would each of the panel members want to see in any future review?

Tony: it needs to be redrafted and made clearer. The FRC next time should engage more about what is good practice. Iain: that it should be extended across to Europe. Especially with Funds tied to banks. David: he is against further regulation. He is happy with “comply or explain” approach. But it does need to be fleshed out. It’s a bit vague. Not only would he like it extended to Europe but wouldn’t it be nice to have in the US although that is “pie in sky”.

Tom asked does the Code make a RBS (Royal Bank of Scotland) less likely. Tony: No but... Ian – more cynical. Nothing much changed. No evidence that in 5 years time the world will have changed. David: We don’t know what will happen next.

The largely negative response to this question supports my own view that the Code (although an welcome improvement) is just sticking plaster and not the root and branch reform that is needed to stop another Fred the Shred.